
To self build a house in the UK, you typically find and buy a plot, secure planning permission, design the home, arrange a self-build mortgage or other finance, get building regulations approval, choose how you will manage the build (main contractor, package supplier, or project managing trades yourself), build in stages with inspections, and complete with a completion certificate and warranty. Reliefs such as the Community Infrastructure Levy self-build exemption and VAT reclaims can reduce costs if you follow the rules.
This article is a sequential checklist. For a broader overview of costs and pros and cons, see our UK self-build guide, and for plot buying see buying land with planning permission in the UK. Rules differ somewhat between England, Scotland, Wales, and Northern Ireland; this article focuses on England.
Step 1: Set your budget and decide your route
Start with what you can realistically spend, including the plot, professional fees, construction, connections, and a contingency. Then decide how hands-on you want to be. Common routes are:
- Main contractor: one builder manages the whole project to your design.
- Package home: a supplier provides a designed kit or panelized system, such as timber frame or SIPs, often with an erection service.
- Self-managed: you hire and coordinate individual trades. This can save money but demands time and knowledge.
- Custom build: a developer provides a serviced plot and you choose a design from a range.
Step 2: Register for Right to Build
In England, local councils keep self-build and custom housebuilding registers under the Right to Build legislation. Joining your council’s register signals demand and may give you information about plots. Registration does not guarantee a plot, but it is free or low-cost in many areas.
Step 3: Find a plot
Sources include plot-finding websites, estate agents, auctions, councils, and local networks. Check whether the plot has planning permission (full or outline), access, services (water, electricity, drainage), ground conditions, and any restrictive covenants. A plot without planning permission is cheaper but riskier.
Step 4: Secure planning permission
If the plot only has outline permission, you will need reserved matters approval for details such as design and layout; otherwise you may apply for full permission for your own design. An architect or planning consultant can advise on what is likely to be approved. Planning conditions often need to be discharged before work starts.
Step 5: Finalise design and get building regulations approval
Planning permission covers what can be built; building regulations cover how it is built, including structure, fire safety, insulation, and drainage. You can use local authority building control or a registered building control approver. Detailed construction drawings and structural calculations are usually needed.
Step 6: Arrange finance
Self-build mortgages differ from standard mortgages because money is released in stages as the build progresses. Some products release funds after each stage is completed (in arrears), while others release funds in advance of each stage, which can ease cash flow. Lenders usually want planning permission, building regulations approval, detailed costings, and a structural warranty or professional supervision arrangement. A specialist mortgage broker can help.
Step 7: Claim the CIL self-build exemption before starting
Where a council charges the Community Infrastructure Levy, self-builders can often apply for an exemption. The claim and required forms must normally be submitted and acknowledged before work begins, and there are conditions about living in the home afterward. Missing the procedure can make the full levy payable, so check your council’s guidance carefully.
Step 8: Build the house
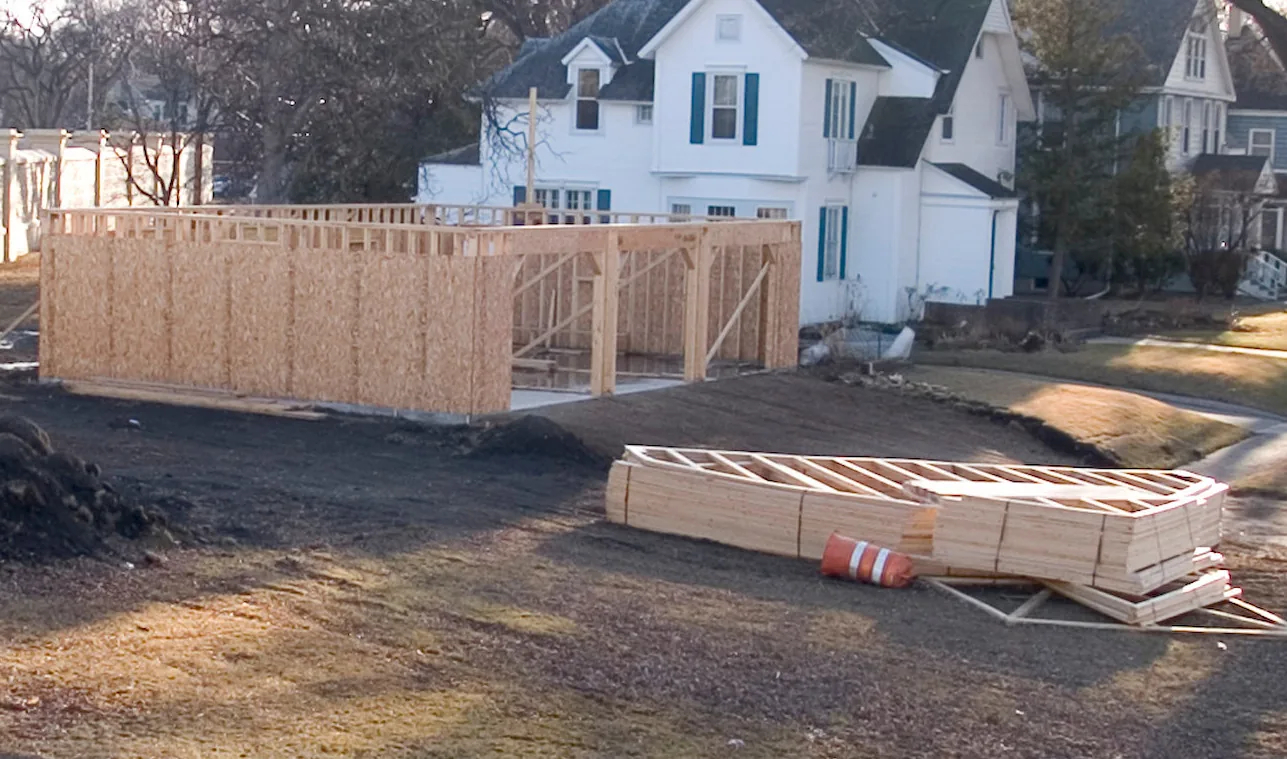
Typical stages include site setup, foundations, superstructure, roof, windows and doors, first fix services, plastering, second fix, and finishes. Building control will inspect at key points. Keep careful records, photos, and invoices, which help with VAT reclaims and warranty requirements.
Step 9: Reclaim VAT where eligible
Construction of a new dwelling is generally zero-rated for VAT when carried out by VAT-registered builders. For materials you buy yourself, HM Revenue and Customs operates a VAT refund scheme for DIY housebuilders. Claims have a deadline after completion and require original VAT invoices, so read HMRC’s guidance at the start of the project, not the end.
Step 10: Completion and warranty
When the work is done, building control issues a completion certificate. Lenders and future buyers generally expect a structural warranty or architect’s certificate. Arrange this before work starts, since warranty providers inspect during construction.
How long does a UK self build take?
Timeframes vary with planning, design complexity, build method, and weather. Off-site manufactured systems can shorten the time on site, but the planning and design phase often takes longer than first-time self-builders expect.
What mistakes do self-builders make?
- Underestimating costs for groundworks and service connections.
- Starting work before discharging pre-commencement planning conditions or claiming CIL exemption.
- Choosing finance that does not match their cash flow.
- Changing the design mid-build.
- Not keeping VAT invoices in the correct form.
Which build method should you choose?
Traditional masonry construction is widely understood by UK builders and lenders. Timber frame, structural insulated panels (SIPs), and other off-site systems can be faster to make weathertight and can deliver strong energy performance, but they need precise design upfront and a supplier with a good track record. Insulated concrete formwork suits some sites and basements. Whatever you choose, confirm that your lender and warranty provider accept the system and ask suppliers for references from completed self-build homes you can visit.
How do you connect services to a self-build plot?
Apply early to the water company, electricity distribution network operator, and gas supplier if needed, since quotes and connection dates can take time. Drainage may connect to a public sewer or need an approved off-mains system such as a treatment plant. Broadband providers may also need to plan a new connection. Connection charges vary widely by location, so get quotes before you finalise the budget.
Frequently asked questions
Do I need planning permission to self build?
Yes, a new dwelling requires planning permission in almost all cases.
Can I get a mortgage for a self build?
Yes. Specialist self-build mortgages release funds in stages.
Can self-builders reclaim VAT?
Eligible self-builders can use HMRC’s DIY housebuilders scheme for qualifying materials, subject to its rules and deadline.
Do I have to pay CIL on a self build?
Often you can claim an exemption, but you must follow the procedure before starting work.